
DEAR VALUED STAKEHOLDERS,
On behalf of the Board of
Directors, I am pleased to
present the Annual Report
of Mycron Steel Berhad and
its group of Companies (“the
Group” or “Mycron”) for the
financial year ended 30 June
2026 (“FY2026”). Despite a
challenging global and domestic
operating environment, Mycron
demonstrated resilience in
FY2026, delivering an improved
financial performance and
ending the year with positive
momentum.
TUNKU DATO’ YAACOB KHYRA
Executive Chairman
OUR BUSINESS AND OPERATIONS
Mycron Steel Berhad operates through two key
manufacturing subsidiaries:
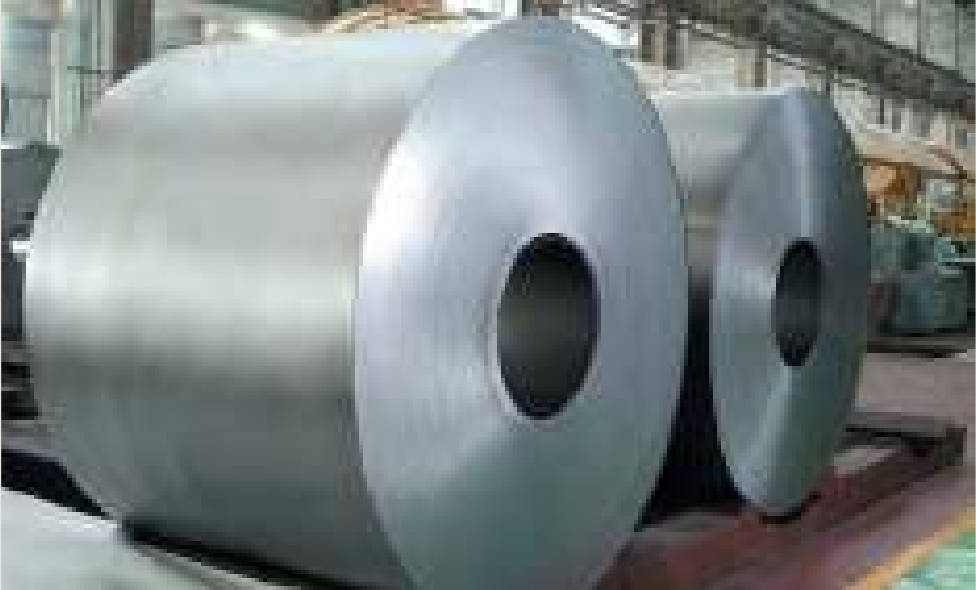
Mycron Steel CRC Sdn Bhd (“MCRC”).
which converts Hot Rolled Coil (“HRC”) steel sheets into
thinner gauge Cold Rolled Coil (“CRC”) steel sheets.
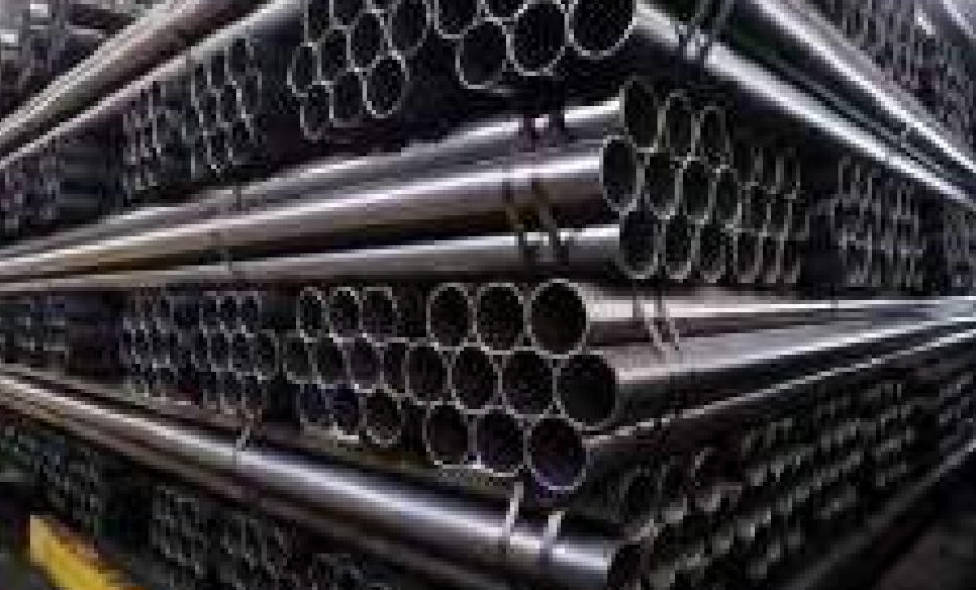
Melewar Steel Tube Sdn Bhd (“MST”),
which manufactures steel tubes and pipes (“Steel Tube”)
using HRC and CRC.
Additionally, the Group’s trading arm,
Silver Victory Sdn Bhd (“SV”), supports the
distribution of steel-related products.
Together, these entities anchor the Group’s
position at the forefront of Malaysia’s
steel industry, serving both domestic and
international markets.
FINANCIAL YEAR OVERVIEW
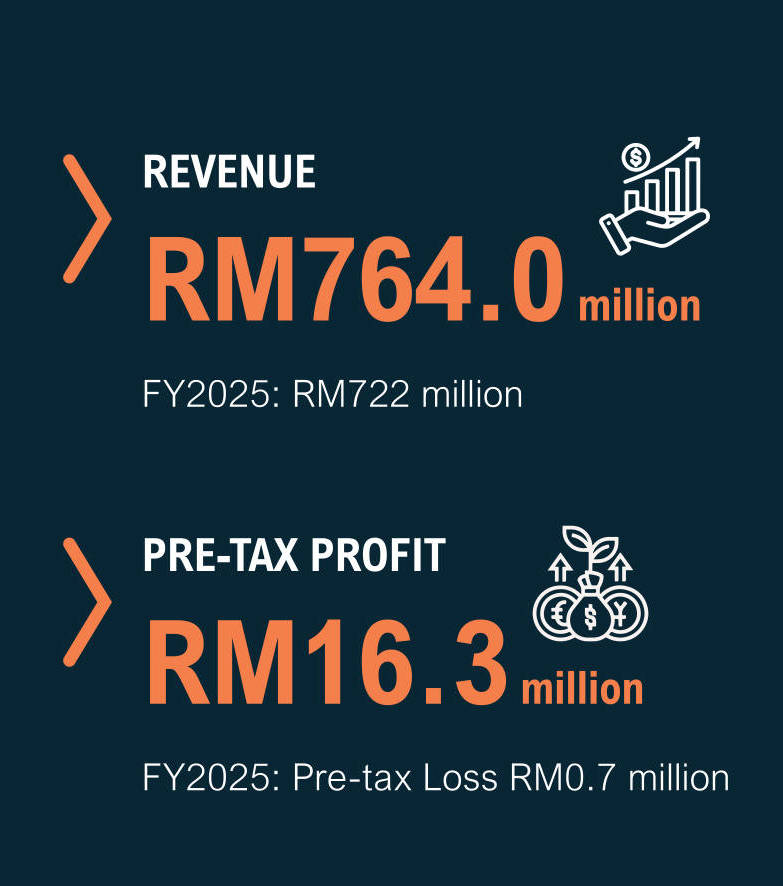
For FY2026, the Group recorded revenue of RM764.0 million, compared with RM722.0 million in FY2025. More significantly, the Group returned to profitability, recording a pre-tax profit of RM16.3 million compared with a pre-tax loss of RM0.7 million in the preceding financial year. The improvement reflected stronger sales volumes and operating performance despite continued pressure from softer steel prices and a highly competitive market environment.
In the first financial quarter, the Group recorded revenue of RM203.1
million, up from RM167.8 million in the preceding quarter, supported
by higher sales volumes across both the CRC and Steel Tube
divisions. Together with higher investment gains and lower interest
costs, the improved performance resulted in a pre-tax profit of RM5.6
million, compared with a pre-tax loss of RM0.8 million in the preceding
quarter.
In the second financial quarter, revenue moderated to RM187.4
million, mainly due to lower average selling prices in line with the
prevailing downward trend in steel prices. The Steel Tube division
recorded improved gross profit, supported by higher sales volume and
production throughput, while the CRC division experienced margin
pressure as export sales softened amid increasing trade barriers
and tariff-related uncertainties in the United States. Notwithstanding
a foreign exchange loss of RM0.4 million, the Group recorded a
stronger operating performance. Higher interest income and lower
interest costs further supported a pre-tax profit of RM5.0 million for
the quarter.
The third financial quarter saw revenue decline to RM157.6 million,
with demand affected by the seasonal slowdown surrounding the
Chinese New Year and Hari Raya festive periods. Despite the softer
revenue, overall sales volume increased while average unit selling
prices declined, reflecting the continued weakness in steel prices.
Both the CRC and Steel Tube divisions recorded higher sales
volumes, although the benefit was offset by lower selling prices.
Margin compression was particularly pronounced in the CRC division.
Consequently, the Group recorded a marginal pre-tax loss of RM0.15
million for the quarter, although year-to-date profitability remained
positive.
Performance strengthened in the fourth financial quarter, with revenue
rising to RM215.9 million, supported by improved sales volumes
across both divisions, led by the CRC division. Higher production and
sales throughput contributed to improved gross margins, while firmer
steel prices during the early part of the quarter improved raw material
to-selling price spreads and supported buying interest. Consequently,
the Group recorded a pre-tax profit of RM5.8 million for the quarter.
Overall, Mycron’s ability to generate profits against a difficult backdrop
demonstrates the continuous improvement that has taken place in
Mycron over many years. Through consistent focus and discipline
on cost competitiveness, manufacturing optimisation, strategic
investments to reduce energy dependence and reduce our carbon
footprint, Mycron has become a stronger and more resilient business.
Most importantly, we have committed and talented employees that
make these achievements possible.
ECONOMIC LANDSCAPE
The last twelve months have been a reminder of how quickly the global operating environment
can change in ways we least expect. The financial year ended 30 June 2026 unfolded against
heightened geopolitical tensions, an increasingly fragmented global trading system, and
persistent uncertainty across major markets. While the global economy remained resilient,
growth was uneven, with elevated operating costs and increasingly protectionist trade policies
weighing on investment, business confidence, and international trade.
Globally, geopolitical tensions and conflicts have intensified.
For the steel industry, market pressures mount as global
capacity reaches new highs and trade circumvention
accelerates.
For the steel industry, these challenges were compounded
by persistent global excess capacity and subdued demand.
The World Steel Association projected global steel demand to
grow by only 0.3% in 2026 to approximately 1.72 billion tonnes,
following a prolonged period of weakness across several
major steel-consuming markets. Against this backdrop, excess
production capacity continued to exert significant pressure on
steel prices and industry margins.
China’s share of global excess capacity rose, spilling surges
of exports to international markets. This surge of exports is
putting enormous pressure on the international steel markets
by displacing domestic production across the world. China’s
steel exports reached a record high of 131 million tonnes in
2025 which have triggered significant trade policy responses
from countries.
At the same time, trade barriers in major consuming markets
became increasingly restrictive. In June 2025, the United
States increased its Section 232 tariffs on most steel imports
from 25% to 50%, while other economies strengthened or
introduced additional trade-protection measures. These
developments further altered established trade flows and
increased the risk of surplus steel being redirected towards
more accessible markets, including ASEAN. Malaysia’s
relatively open trading environment consequently remained
exposed to greater import pressure and increasingly
competitive regional steel flows.
As the year progressed, geopolitical risks intensified further
with the escalation of conflict in the Middle East. Rising
energy and commodity prices, together with constraints
affecting passage through the Strait of Hormuz, added
further uncertainty to global supply chains and the movement
of critical raw materials. These developments introduced
additional downside risks to global growth and steel demand
while heightening concerns over energy and raw-material
security for energy-intensive industries such as steel.
Against this volatile external environment, Malaysia’s broader
economy remained resilient. The economy expanded by
5.2% in 2025, supported by domestic demand and continued
growth in the services and manufacturing sectors, while
growth of 5.4% was recorded in the first quarter of 2026.
However, the positive headline economic performance did
not translate proportionately into improved conditions for
domestic steel manufacturers, as regional overcapacity,
high import penetration, and persistent price competition
continued to weigh on industry margins.
The Malaysian Government also continued to address
longer-term structural issues within the domestic steel
industry, including capacity management, investment quality,
licensing requirements, and the transition towards lower
carbon production. Greater policy coordination, effective
trade measures and disciplined management of industry
capacity will be increasingly important to ensuring that future
investment supports higher-value production without further
aggravating existing supply-and-demand imbalances.
Overall, FY2026 was characterised by weak global steel
demand, record export activity from China, increasingly
restrictive trade measures, and heightened geopolitical
uncertainty. These factors combined to create significant
pricing and margin pressures for steel producers throughout
the year. Against this challenging backdrop, the Group
remained focused on strengthening operational efficiency,
maintaining cost discipline, broadening its market reach, and
safeguarding its long-term competitiveness.
DOMESTIC CRC INDUSTRY STRUCTURE
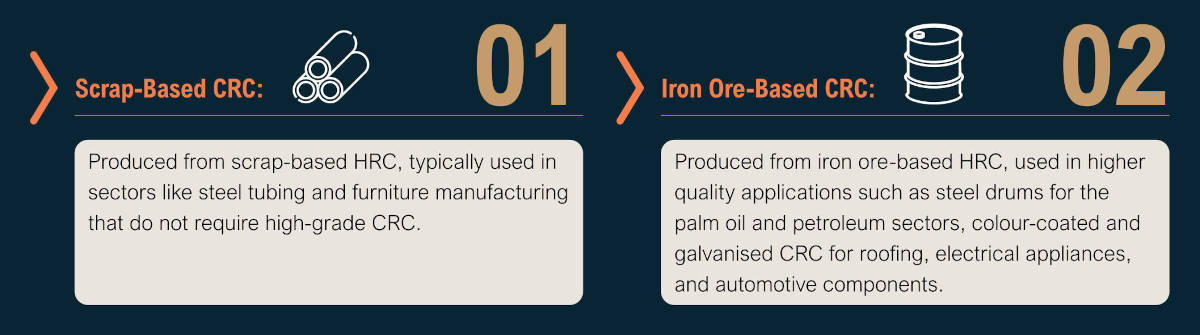
Hot Rolled Coil (“HRC”) steel sheets are the fundamental raw material used in producing Cold Rolled Coils (“CRC”) steel
sheets. In general, CRC manufacturers produce two types of CRC:
As one of the few fully operational Malaysian-owned and managed steel groups, Mycron takes immense pride in the
legacy and resilience of its businesses. MST has served the Malaysian steel industry for more than 55 years, while
MCRC has built a strong track record spanning more than 35 years. Together, these businesses have contributed to
Malaysia’s industrial development, supported local manufacturing capabilities, and helped build domestic steel expertise
over several decades.
This long-standing presence reflects the strength, experience and commitment of the Group through multiple industry
cycles and changing market conditions, while reinforcing Mycron’s continued role in supporting Malaysia’s domestic
steel manufacturing capabilities.
OVERALL MOVEMENT OF FLAT STEEL IN MALAYSIA
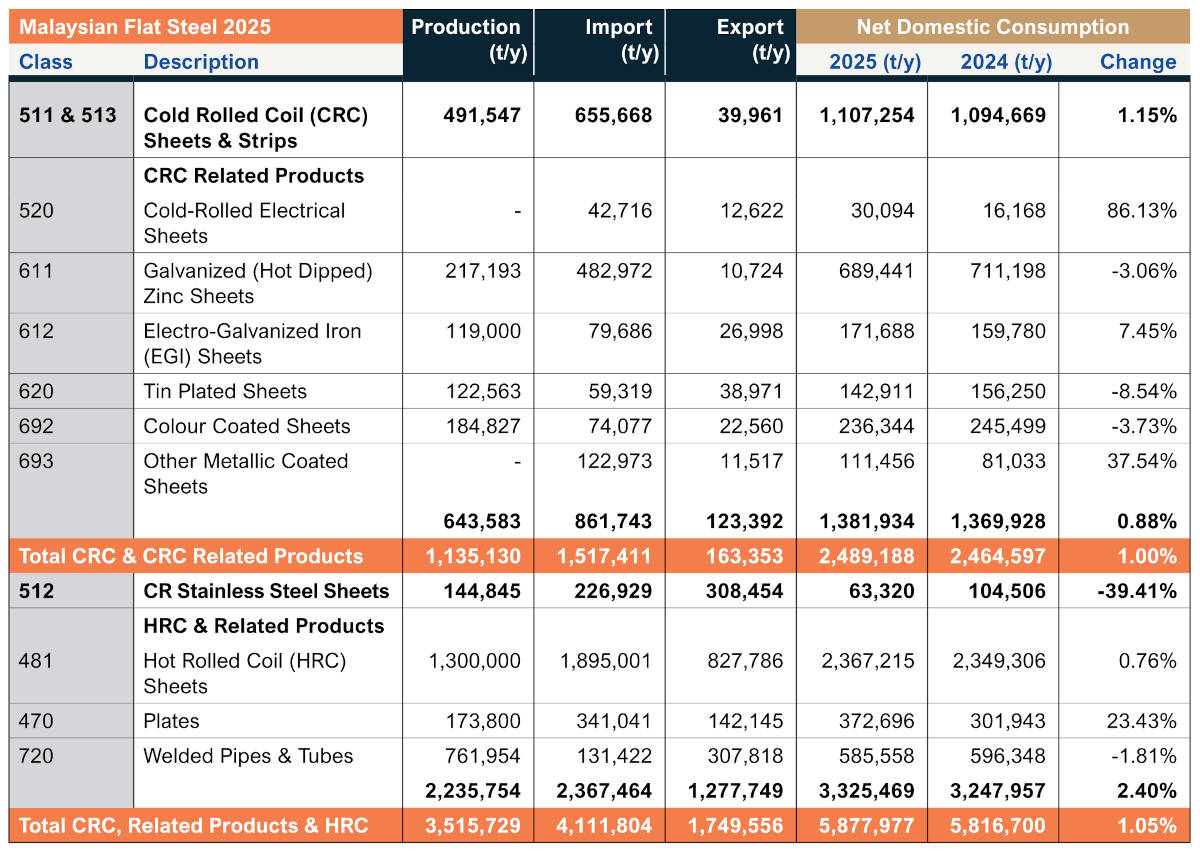
Overall Movement of Flat Steel in Malaysia by Calendar Year
(Source: Malaysia Iron and Steel Industry Federation, MISIF)
The table above provides a summary of the overall movement of
flat steel in Malaysia for calendar year 2025, with comparative
figures for 2024. Malaysia’s flat steel market recorded net
domestic consumption of 5.88 million tonnes in 2025, up
marginally by 1.05% from 5.82 million tonnes in 2024. Growth
remained modest across most product categories. Total
local production stood at approximately 3.52 million tonnes,
equivalent to around 60% of net domestic consumption, while
imports of approximately 4.11 million tonnes were equivalent
to nearly 70% of domestic consumption, highlighting the
significant presence of imported steel products in the
Malaysian market.
Within the Group’s core segments, net domestic consumption
of CRC Sheets and Strips (Class 511 & 513) increased by
1.15% to 1.107 million tonnes. Imports of 0.656 million tonnes
represented close to 60% of domestic consumption, compared
with local production of 0.492 million tonnes, reflecting the
continued high level of imports in this product category.
In the Welded Pipes and Tubes segment (Class 720),
net domestic consumption declined marginally by 1.81%
to approximately 0.586 million tonnes. Local production
stood at approximately 0.762 million tonnes, with exports
of approximately 0.308 million tonnes and imports of
approximately 0.131 million tonnes. These figures reflect a
market in which domestic demand remained relatively soft,
while export activity continued to account for a significant
portion of industry output.
Despite Malaysia’s established domestic production
capabilities, imports remain high and the industry continues
to face supply-demand imbalances and competitive pressure
from imported steel products. Mycron remains actively
engaged with the Malaysian Government and relevant
agencies in support of effective trade remedies and consistent
enforcement against unfair trade practices, including dumped,
subsidised and illicitly imported steel products, with the
objective of promoting fair competition and a level playing
field for domestic producers.
OUR COMMITMENT TO
GOVERNANCE
The Board of Directors recognises that strong corporate
governance is fundamental to maintaining stakeholder
confidence and supporting the long-term sustainability
of the Group. We remain committed to conducting our
business with integrity, accountability, and transparency, in
line with established corporate governance principles and
best practices.
The Board and senior management are committed to
upholding high standards of corporate governance and
business ethics across the Group’s operations. Our
governance framework is supported by, among others, the
Board Charter, Terms of Reference for Board Committees,
Anti-Fraud and Anti-Corruption Policy, Fit and Proper Policy,
Communication Policy, Conflict of Interest Policy, and
Corporate Disclosure Policies and Procedures.
SUSTAINABILITY
Operating sustainably is integral to Mycron’s long-term business strategy. We remain
committed to embedding sustainability principles across our governance, environmental
stewardship, social responsibility and economic performance.
Our sustainability agenda is championed by the Group Chief
Executive Officer, with oversight from senior management
through the Sustainability Oversight Committee, ensuring
that sustainability considerations are incorporated into key
business decisions and operational practices.
Our sustainability priorities are aligned with Malaysia’s
broader transition towards a more sustainable and
competitive economy, including key national frameworks
such as the National Energy Transition Roadmap (NETR),
the New Industrial Master Plan 2030 (NIMP 2030) and
the Circular Economy Policy Framework. Further details
on the Group’s sustainability objectives, initiatives and
performance are provided in our Sustainability Report.
A significant milestone during the year was the attainment of
Environmental Product Declarations (EPDs) by both Mycron
Steel CRC Sdn Bhd and Melewar Steel Tube Sdn Bhd.
The EPDs provide transparent and independently verified
information on the environmental impact of our products
across their life cycle, strengthening the Group’s carbon
transparency and environmental credentials.
This achievement is increasingly relevant as customers,
regulators and supply-chain partners place greater
emphasis on the embodied carbon and environmental
footprint of steel products. Regulatory developments
such as the European Union’s Carbon Border Adjustment
Mechanism (CBAM), together with the broader evolution of
carbon-pricing frameworks, are expected to make carbon
intensity an increasingly important consideration for market
access and long-term competitiveness.
Mycron continues to support the transition towards a lower
carbon economy through targeted investments in renewable
energy, energy efficiency and process optimisation. We are
approaching this transition in a measured and pragmatic
manner, balancing our decarbonisation ambitions with
commercial realities while continuing to strengthen the
resilience and competitiveness of our operations.
For Mycron, the objective is not merely to respond to
evolving regulatory requirements, but to position the Group
competitively for a future in which carbon transparency
and lower-emission production will increasingly influence
purchasing decisions and market access. The attainment of
EPDs by both our CRC and Steel Tube divisions marks an
important step in this journey and supports our longer-term
ambition to become a leading producer of lower-carbon
steel products in Malaysia.
PROSPECTS AND OUTLOOK
The iron and steel industry
remains a fundamental pillar of
the national economy, supporting
infrastructure development,
manufacturing activity and
Malaysia’s broader industrial
growth. While the industry
continues to face an increasingly
complex operating environment
and significant headwinds at the
global, regional and domestic
levels, steel will remain integral to
economic development. Against
this backdrop, the Group believes
that meaningful opportunities
remain for Mycron over the
longer term.
The Group ended the financial year on a stronger footing,
with performance improving progressively across the year.
Sales volume increased by 19.5% year-on-year, although unit
margins remained broadly flat. Domestic steel demand was
generally resilient throughout the year, albeit the seasonal
slowdown during the double-festive period in the third quarter.
The downward trend in steel prices that began in 2022
showed signs of stabilising during much of the financial year,
before rebounding towards the end of March amid heightened
geopolitical developments in West Asia. Nevertheless, the
Group’s margins remained under pressure from elevated
production and operating costs, including the expanded Sales
and Service Tax, energy, utilities and transportation costs, as
well as intense price competition from imported steel products
and an increasingly demanding regulatory environment.
While Malaysia’s headline economic indicators remained
encouraging, supported by growth in sectors such as data
centres, semiconductors, electrical and electronics, and
tourism, operating conditions have remained challenging
for parts of the broader private sector. Small and medium
enterprises, traditional manufacturing, retail and supporting
industries in particular continue to contend with rising
operating costs, increased foreign competition and softer
order books. Industry surveys and feedback from our
customers similarly point to continued pressure on business
costs and margins, with some businesses responding through
cost rationalisation, downsizing, or relocation.
Looking ahead to the next financial year, domestic steel
demand is expected to remain supported, albeit at a more
moderate pace. Near-term conditions are likely to remain
challenging as steel prices soften and buyers adopt a more
cautious purchasing approach amid continued geopolitical
uncertainty. At the same time, the domestic market may face
greater competitive pressure from imported steel products
as excess regional capacity and trade diversion intensify,
particularly as major export markets introduce increasingly
restrictive trade measures. These conditions are expected to
continue weighing on the margins of domestic steel producers,
particularly where local cost structures remain elevated
relative to regional competitors. Against this backdrop, the
outlook for the coming financial year remains cautiously
challenging.
Nevertheless, the Group will continue to build on the momentum achieved during
the year by strengthening its position in the domestic market while selectively
pursuing opportunities in overseas markets. At the same time, we will continue to
advocate for a fair and competitive domestic marketplace and remain disciplined
in managing costs, improving operational efficiency and protecting margins.
Policymakers in many regions are taking decisive action to address steel
overcapacity, support domestic manufacturing, and reinforce the strategic
importance of self-sufficiency. In 2026, this is most evident in Europe, where the
introduction of CBAM and a strengthened tariff rate quota (TRQ) framework are
beginning to affect Mycron’s exports to Europe. In response, Mycron is adapting
by diversifying its market base, strengthening its competitiveness, and reducing
reliance on individual markets and sectors, thereby enhancing the Group’s
resilience to external shocks.
For many years, Malaysian steel producers have faced the challenge of rising
imports. Policy measures are needed to address this imbalance. Malaysia should
consider measures similar to the European TRQ framework, which establishes a
more granular and robust quota system aimed at managing import volumes and
reducing excessive import dependence. Such measures could support higher
capacity utilisation among domestic steel manufacturers, and, in turn, improve
the industry’s overall competitiveness and financial sustainability.
At the same time, the transition towards lower-carbon manufacturing is becoming
an increasingly important determinant of competitiveness and market access.
Mycron is working to better understand and manage Scope 3 emissions across
our value chain, while continuing to reduce the carbon intensity of our own
manufacturing operations through reductions in Scope 1 and Scope 2 emissions.
Our efforts include energy efficiency and conservation, renewable energy,
waste reduction and leaner manufacturing practices. We are also strengthening
transparency and product-level carbon traceability through initiatives such as
Environmental Product Declarations (EPDs) and CBAM reporting.
We remain steadfast in our commitment to supporting the transition towards
a lower-carbon economy. Our approach is pragmatic and focused on creating
long-term value, while continuing to reduce the carbon intensity of our own
operations. Looking ahead, I remain optimistic about Mycron’s prospects. The
momentum within the Group is positive, and steel’s strategic importance is
increasingly being recognised by policymakers around the world. As an infinitely
recyclable material, steel is fundamental to the global circular economy and
will remain indispensable to economic development, infrastructure, and the
transition towards a more sustainable future.
DIVIDEND
In view of the Group’s financial
position, the Board of Directors does
not recommend the payment of any
dividend for the financial year ended 30
June 2026.
ACKNOWLEDGMENT AND APPRECIATION
On behalf of the Board, I would like to
express my sincere appreciation to
our management team and employees
for their dedication, resilience, and
continued commitment throughout the
year.
I would also like to extend our gratitude
to our customers, business partners,
shareholders, and other stakeholders
for their continued trust and support.
Your confidence in Mycron remains
invaluable as we continue to strengthen
the Group and position ourselves for the
opportunities ahead.
As we move forward, we remain focused
on navigating the challenges before
us with discipline and resilience, while
building a stronger, more sustainable
and competitive Mycron for the future.
Tunku Dato' Yaacob Khyra
Executive Chairman